Phantom gains: Crypto tax rules are changing, but not for those already caught
ACT and Inland Revenue confirm the coming crypto tax changes, as proposed, won't help people already owing tax on gains that have since vanished.

"Some now owe more in tax than their entire portfolio is worth."
Kiwis who already owe tax on cryptocurrency gains they have since lost will not be helped by the government's tax bill or by ACT's election policy of a 12-month bright-line rule, as both are proposed.
The tax changes now before Parliament would only "apply prospectively from 1 April 2027", not to earlier years, Inland Revenue told Cryptocurrency NZ.
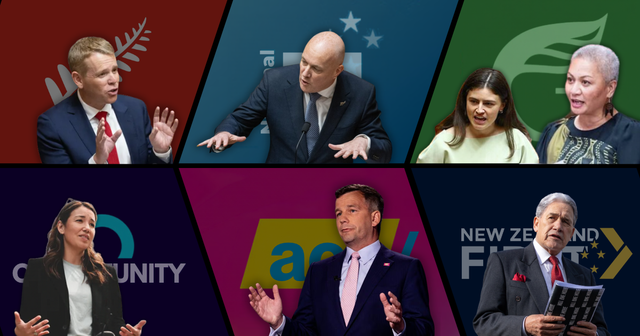
ACT's crypto election policy, launched in August, would stop taxing gains on personal crypto investments held for longer than 12 months.
Cryptocurrency NZ asked ACT whether that rule would apply retrospectively.
ACT deputy leader Nicole McKee said it would apply from the day the law takes effect.
"The new rule would not automatically reopen or cancel tax liabilities arising from disposals made in previous income years."
These tax debts come from what the community calls phantom gains. Swapping one crypto for another is taxed like a sale; so tax can fall due on gains never turned into dollars, and still be owed after the market wipes those gains out.
In June, CNZ reported on a New Zealander who posted on r/NZBitcoin he owed roughly $70,000 in tax on gains he no longer had.
"So you can end up with a large tax bill despite having very little left," TaxHawk director Josh Hawkey said.
Inland Revenue has not measured how many people are in that position.
In response to an Official Information Act (OIA) request from Cryptocurrency NZ, the IRD said it had done no internal assessment of these cases.
Relief is still possible.
Those already caught can ask Inland Revenue to write off their tax debt, which it says it may do "where appropriate".
Hawkey warned this "isn't an automatic write-off": they must show serious hardship, with Inland Revenue looking at their income, expenses and assets.
Proposed changes offer nothing for existing debts
ACT gave the clearest answer.
McKee said past bills would stay under the old rules.
"Those liabilities would remain subject to the law that applied at the time, unless Parliament expressly provided otherwise."
"ACT recognises that some New Zealanders have incurred tax liabilities on cryptocurrency gains that were subsequently lost as the market fell," McKee said.
Mckee said the 12-month rule was not a promise of prospective tax relief.
"It is not, in itself, a commitment to write off existing tax liabilities or introduce a retrospective loss carry-back scheme."
Any relief "would need to be considered separately, including its fairness, fiscal cost and interaction with existing rules for deducting losses".
"The 12-month holding period would count from the original acquisition of the asset, including time held before the law changes," McKee said.
Crypto-to-crypto swaps are less clear.
Asked whether swapping one crypto for another would restart the 12-month clock, ACT said: "The policy's specific details remain to be developed and will be informed by further advice."
Swaps are what create phantom gains.
Inland Revenue made no promise either. On people whose tax bill is bigger than what they have left, it said: "We consider each customer's individual facts and circumstances when dealing with crypto-related tax debt."
At a BlockchainNZ webinar on the bill on 12 October, an Inland Revenue official said the starting presumption was that "legislation applies prospectively", but that "there are grounds to do things retrospectively", noting other parts of the bill already are. Submissions asking to backdate changes would need to make a detailed case, with fiscal cost a key consideration.
Explaining why the bill's crypto changes were narrow, one official said they had been "effectively instructed by the Minister" to look at "what can we do quickly that doesn't have a high fiscal cost", while reducing compliance costs.
Asked whether there was any way to know what making the changes retrospective would cost, an official said: "We have very limited information."
Industry and tax advisers want relief
Blockchain NZ, the industry body that hosted the webinar, will use part of its submission to ask for the crypto changes to apply retrospectively.
"Fixing the rules from 2027 does nothing for the people already holding tax bills under the old rules," BlockchainNZ executive director Trevor Topfer said.
Topfer said the submission would be public, and that phantom gains affected "thousands of ordinary Kiwis". Inland Revenue holds no figures that could confirm or rule that out.
"Some now owe more in tax than their entire portfolio is worth," he said.
"That isn't tax avoidance; it's the system taxing money people never had."
Optima Chartered Accountants director Matt Shallcrass said there was "an argument for targeted retrospective relief", especially where investors with large tax bills then suffer large losses.
His suggestion would not cancel old bills.
"Allowing qualifying realised crypto losses to be offset against earlier taxable gains could provide a fairer outcome, without simply writing off historical tax liabilities," he said.
That would close a gap Hawkey described.
"While losses can generally be offset against other taxable income or carried forward, they can't ordinarily be carried backwards to offset the previous year's gains," he said.
Hawkey said his firm sees clients whose tax bill is bigger than what they have left in crypto. "We certainly see this, particularly following periods of significant market volatility."
For those clients, the options are paying in instalments or applying for relief on serious hardship grounds. "That isn't an automatic write-off, though," he said.
More tax letters, but no count of phantom gains
The IRD sent 1,866 crypto-related letters across the 2024 to 2026 income tax years, according to its response to CNZ's OIA request.
Of those, 1,572 were in the 2026 income year alone.
Most were education letters, 1,300 of them sent in April 2026. Another 515 were targeted compliance letters to specific taxpayers.
Inland Revenue has had data from New Zealand crypto exchanges since 2021, and said its response to undeclared crypto income "is scaling up".
The IRD has not undertaken any specific internal assessment of crypto-to-crypto income cases," the response said.
It said phantom gains cases "appear to be becoming less common" as investors learn the rules.
Asked by CNZ what that was based on, Inland Revenue said the observation "was anecdotal in nature", drawn from the "observations and personal experience" of its specialist staff.
It does not record tax debt by the type of income behind it, so it could not say how much is owed on crypto.
Offshore exchange data arrives in 2027
Inland Revenue is about to get more data.
New Zealand crypto platforms have had to collect user data under the Crypto-Asset Reporting Framework (CARF) since 1 April 2026, with the first report due to Inland Revenue by 30 June 2027, Cryptocurrency NZ reported in March.
Data on New Zealanders using overseas exchanges follows.
Seventy-four countries have agreed to take part, and New Zealand "will start to get CARF data in late 2027", Inland Revenue said in its OIA response.
It said it would "adapt our approach depending on what the data is telling us", and that "a big part of this will be education focused".
Inland Revenue told CNZ it "expects there will be greater interaction with NZ tax residents who have used overseas crypto-asset service providers", depending on compliance levels and the quality of the data.
Submissions on the bill are open, and the Finance and Expenditure Committee has asked for views by 1 December, 2026.